Last updated: 24 September 2026
This article is general guidance on the Construction Industry Scheme and is not advice on a specific contract or a specific worker. Employment status turns on the facts of each engagement, and CIS rules change. Confirm the current position on GOV.UK and take advice before you rely on any of it.
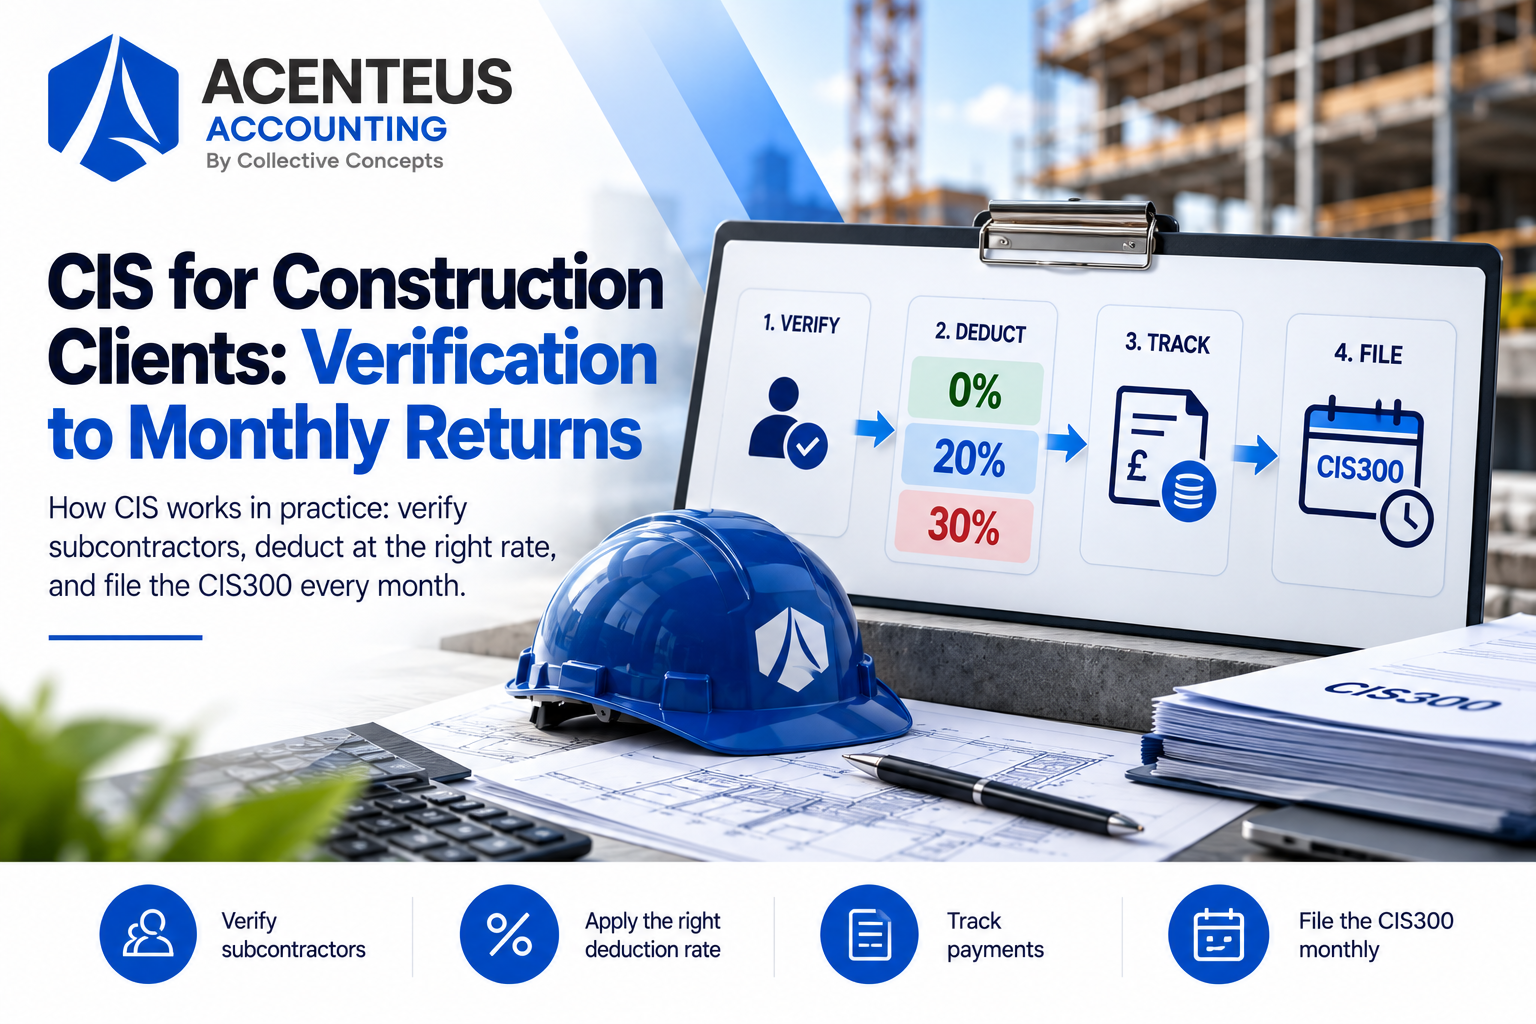
The Construction Industry Scheme runs on a monthly cycle with four fixed points. You settle employment status before anything else, you verify the subcontractor with HMRC to get a deduction rate, you work out the deduction on the labour element only and issue a payment and deduction statement within 14 days of the end of the tax month, and you file the CIS300 and pay HMRC by the 19th. Miss the return by a single day and the penalty is £100. Everything else in CIS is detail hanging off those four points.
Most CIS guidance online treats the scheme as a tax question. It is not. It is an operating process with a deadline every month, and the expensive failures are almost never technical. They are a subcontractor who should have been on payroll, a materials figure taken on trust, a reverse charge invoice processed as if it carried VAT, or a nil month nobody filed. This article walks the cycle in the order you actually have to do it.
Key takeaways
- Employment status comes first, and off-payroll working comes before CIS. Where PAYE applies under the off-payroll rules, HMRC says you do not consider CIS at all.
- Being registered for CIS is not proof of self-employment. HMRC states that plainly in its Business Income Manual.
- Deduct 20 percent for a verified registered subcontractor, 30 percent if they cannot be verified or are not registered, 0 percent for gross payment status.
- The deduction applies to labour only. Take off VAT, materials the subcontractor paid for, consumable stores, fuel that is not travel, plant hire and prefabrication before you apply the rate.
- Payment and deduction statements are due within 14 days of the end of each tax month, so the 19th in practice.
- The CIS300 is due by the 19th of the month following the tax month. Late penalties run £100, £200, then £300 or 5 percent, up to £3,000 or 100 percent beyond 12 months.
- A month with no payments still needs a nil return or an inactivity request. Silence is a late return.
- The VAT domestic reverse charge sits on top of CIS for most standard rated and reduced rated construction work between VAT and CIS registered businesses.
- A non-construction business becomes a deemed contractor once it spends more than £3 million on construction in the previous 12 months.
- Keep CIS records for at least three years after the end of the tax year, with a penalty of up to £3,000 for failing to produce them.
Who is a contractor, and who becomes one without noticing
Two routes into the scheme. The obvious one is the mainstream contractor: a business whose trade is construction and which pays subcontractors to do construction work. That business must register for CIS before it takes on its first subcontractor, not before its first return.
The second route catches people out. A business that does no construction at all becomes a deemed contractor once its spend on construction operations passes £3 million in the previous 12 months. It is a rolling test, not a financial year test. Property investors, retail groups fitting out sites, housing associations and manufacturers doing a plant expansion all fall into it, usually without anyone in finance realising the threshold has been crossed. The first sign is often an HMRC letter.
If you advise a client with a capital programme of that size, the £3 million test belongs on the management accounts review, not in a tax memo somebody reads once a year. It is a running total, and the obligation starts when it is breached, which is one of the reasons a capital programme of that size usually needs an outsourced finance function watching the numbers monthly rather than a year end review catching it late.
What counts as construction operations
The definitions sit in CIS 340, HMRC’s guide for contractors and subcontractors. The scope is wider than most people expect on the inclusions and narrower on the exclusions.
| Inside CIS | Outside CIS |
|---|---|
| Site preparation, groundworks and demolition | Architecture and surveying |
| Construction, alteration, repairs and extensions | Scaffolding hire where no labour is supplied |
| Installation of heating, lighting, power, water and ventilation | Carpet fitting |
| Decorating and internal cleaning after construction work | Making materials used in construction, off site |
| Dismantling of structures and works forming part of the land | Delivering materials |
| Repairs and finishing integral to the project | Canteens, hostels, security, medical and site facilities |
The two that generate the most arguments are scaffolding and materials manufacture. Scaffolding hire on its own is outside the scheme, but the moment the hire comes with erection labour it is inside. Making a component in a factory is outside, fixing it on site is inside. Where an invoice covers both, the construction element is inside CIS and the rest is not, and the invoice needs to be readable enough to tell them apart. Ask for that split at the point you onboard the subcontractor and you will never have to reconstruct it later.
Step one is employment status, and it comes before CIS
This is the step almost every CIS article skips, and it is the one that carries the largest bill when it goes wrong. CIS is a deduction mechanism for payments to self-employed subcontractors. It has nothing to say about whether the person is genuinely self-employed. Register someone for CIS, deduct 20 percent, file the return, and if they were in substance an employee you have an unpaid PAYE and National Insurance liability sitting behind a scheme that looked compliant on its face.
HMRC puts it without hedging in its Business Income Manual: being registered as a CIS subcontractor is not proof of self-employed status. The manual then tells its own officers what to look for, and the list is a useful self-check. Accounts with no purchases, no plant, no non-family wages and no business expenses. A worker who used to be employed doing the same work, sometimes by the same business. A worker who has only ever worked for one engager. None of those is conclusive on its own. Together they are what an enquiry is built on.
The order of the two regimes
Where the subcontractor works through their own limited company, there is a second regime in play, and the order matters. HMRC’s Employment Status Manual sets it out: consider the off-payroll working rules first. Where payments are subject to PAYE under those rules, you do not need to consider CIS at all. Only if the off-payroll rules do not apply does the party receiving the services go on to consider whether CIS deductions are due.
The small client exception folds into the same sequence. Where the client is small for off-payroll purposes, the determination passes to the worker’s own intermediary, but the client still has to consider whether CIS deductions apply to what it pays. So the small client does not get out of the analysis. It gets out of half of it.
In practice that means three questions in order, before a penny is paid. Is this an employee? If not, do the off-payroll rules apply? If not, is the work a construction operation and therefore within CIS? HMRC’s Check Employment Status for Tax tool answers the first two, and HMRC will stand by the result as long as the information given remains accurate and is in line with its guidance. Keep the output. An undated screenshot is not evidence, a saved determination with the answers visible is.
Verification: what HMRC needs and when you can skip it
Verification is how you find out what rate to deduct. You cannot guess it and you cannot take the subcontractor’s word for it. HMRC returns the rate and a verification number, and that number is what protects you if the subcontractor’s status is later disputed.
| Subcontractor type | What HMRC needs |
|---|---|
| Sole trader | Name, Unique Taxpayer Reference and National Insurance number |
| Limited company | Company name, company Unique Taxpayer Reference and company registration number |
| Partnership | Partnership Unique Taxpayer Reference, trading name and nominated partner details |
| You, the contractor | Your UTR, Accounts Office reference and employer reference |
Two operational points. Temporary National Insurance numbers, the ones beginning TN or with two digits, cannot be verified, so a subcontractor presenting one needs a real number before they are paid. And you do not need to verify again if the subcontractor has been included on a CIS return in the current or the last two tax years. That two year window is worth tracking in the payroll record rather than rediscovering each time, because re-verifying unnecessarily costs time and forgetting to verify a genuinely new subcontractor costs 10 percent of their labour value in an over-deduction you then have to unwind.
Where verification fails, the rate is 30 percent. That is not a penalty and it is not permanent. It is the default, and it reverses once the subcontractor registers and is verified successfully, with the excess recovered through their own return rather than through yours.
Working out the deduction
The rate applies to the labour element, never the invoice total. HMRC’s guidance lists what comes off the gross figure first: VAT, consumable stores, fuel that is not travel fuel, plant hire for the job, the cost of manufacturing or prefabricating materials, and materials the subcontractor paid for. The last one needs evidence, which in practice means receipts, and a contractor who accepts a materials figure without them is carrying the risk of it.
| Line | Amount |
|---|---|
| Labour | £4,000.00 |
| Materials the subcontractor paid for, with receipts | £1,500.00 |
| Plant hired for this job | £500.00 |
| Invoice total before VAT | £6,000.00 |
| Amount subject to CIS | £4,000.00 |
| CIS deduction at 20 percent | £800.00 |
| Net payment to the subcontractor | £5,200.00 |
Read that table against the wrong version and the size of the error is obvious. Apply 20 percent to £6,000 and you deduct £1,200, over-deduct by £400 on a single invoice, and hand the subcontractor a cash flow problem they will recover only at the end of the tax year. Apply it to £4,000 and it is right. The difference is entirely in whether the invoice separates labour from everything else, which is why the invoice format is worth agreeing at onboarding rather than arguing about at payment.
Three rates, and only three. 20 percent where the subcontractor is registered and verified. 30 percent where they are not registered or cannot be verified. 0 percent where they hold gross payment status.
The VAT reverse charge sits on top, and it is a separate test
Since 1 March 2021 the VAT domestic reverse charge for building and construction services has changed who accounts for the VAT on most construction supplies. The subcontractor does not charge VAT. The customer accounts for it as both output tax and input tax. Cash never moves. The invoice must say so, with wording such as “VAT Act 1994 Section 55A applies” or “Customer to pay the VAT to HMRC”.
The reverse charge applies only when every one of these is true, so it is a checklist rather than a judgement:
- The customer is registered for both VAT and CIS.
- The services fall within the scope of CIS.
- The supply is standard rated or reduced rated. Zero rated work is outside it.
- The supplier is not an employment business.
- The customer has not given written notification that it is an end user or an intermediary supplier.
The end user rule is the one that catches practices out. Being an end user is optional, and the customer must tell the supplier in writing to be treated as one. A developer building to sell is typically an end user, because it makes no onward supply of construction services. If that notification never arrives, the reverse charge applies by default and the supplier who charged VAT anyway has an invoice to credit and reissue.
The practical failure is at the bookkeeping stage rather than the tax stage. A reverse charge invoice posted as a normal standard rated purchase puts input tax on the return that was never charged. It is a small error repeated monthly, and it compounds quietly. Our note on choosing a VAT scheme and the registration threshold covers the scheme side for construction clients who are near the line.
Payment and deduction statements: 14 days, every month
Every subcontractor you deduct from gets a written statement showing what they were paid and what was deducted, and it is due within 14 days of the end of the tax month. Tax months run from the 6th to the 5th, so for the month ending 5 June the statement is due by 19 June. The deadline lands on the same day as the return, which is the sensible way to run it: one monthly routine, not two.
These statements are the subcontractor’s only evidence of the tax already paid on their behalf. A subcontractor who cannot produce them cannot reclaim, and a limited company subcontractor making an in-year claim has to send copies of all of them. Issuing them late is a small administrative failure at your end and a real cash problem at theirs, which is why it is usually the first thing a subcontractor complains about when they move contractor.
The CIS300 and the 19th
The monthly return goes to HMRC by the 19th of every month following the last tax month. It lists every subcontractor paid, the payments, the deductions and the verification position, and it carries a declaration that employment status has been considered for each of them. That declaration is not decoration. It is the statement HMRC quotes back at a contractor who says nobody ever asked them about status.
| How late | Penalty |
|---|---|
| 1 day | £100 |
| 2 months | £200 |
| 6 months | £300 or 5 percent of the deductions, whichever is higher |
| 12 months | A further £300 or 5 percent, whichever is higher |
| More than 12 months | Up to £3,000 or 100 percent of the deductions, whichever is higher |
The penalties stack rather than replace, and there is an appeal route within 30 days of the notice. The point to hold onto is that the first £100 arrives after one day late, not after a grace period, and it arrives per return. A contractor who forgets three months has £300 before the ladder even starts climbing.
A month with no payments still needs something
If you paid no subcontractors in a tax month you either file a return showing zero, a nil return, or you contact HMRC and ask to be treated as inactive. Doing neither is a late return and attracts the £100. Seasonal contractors and clients with a single project between jobs are the usual casualties, because nothing happened and so nobody thought anything was due.
Getting the deductions back
CIS deductions are advance payments of the subcontractor’s own tax and National Insurance, so the money is not lost. How it comes back depends entirely on the trading structure, and the two routes have very different cash flow profiles. A sole trader waits for the Self Assessment return and the January deadline. A company can recover monthly, if the payroll submission is right.
| Structure | Route back | Timing |
|---|---|---|
| Sole trader or partner | Offset against the Self Assessment liability | After the tax year ends, on the return |
| Limited company | Report deductions suffered on the EPS and set them against PAYE liabilities | Monthly, through payroll |
| Limited company, excess remaining | Refund claim after the tax year ends | HMRC usually responds within 8 weeks |
The limited company route runs through payroll, which is why CIS and payroll should not sit with different people. The company reports the total CIS deductions suffered year to date on an Employer Payment Summary, sent by the 19th, and HMRC reduces that month’s PAYE bill accordingly. It is the same submission that carries the Employment Allowance claim, so a company missing one is usually missing both. A company that never submits the EPS pays its PAYE in full while its CIS credit sits unused, which is a self-inflicted working capital problem and a surprisingly common one.
Where deductions still exceed the PAYE liability at the end of the year, the company claims a refund. HMRC will only process it once all FPS and EPS submissions, all monthly CIS returns if the company is also a contractor, and the Company Tax return have been filed, and usually responds within 8 weeks. In-year claims are allowed in only two situations: the business has stopped trading, or deductions were taken after a move to gross payment status. Both need copies of every payment and deduction statement for the year.
Gross payment status and the three tests
Gross payment status removes the deduction entirely, which is why it is worth chasing for any subcontractor of size. Three tests, all of which must be met.
| Test | What it requires |
|---|---|
| Business | Construction work or supply of labour for it, in the UK, run through a bank account |
| Turnover, sole trader | At least £30,000, excluding VAT and the cost of materials |
| Turnover, partnership | £30,000 per partner, or £100,000 for the whole partnership |
| Turnover, company | £30,000 per director, or £100,000 for the whole company |
| Turnover, close company | £30,000 for each person, where five or fewer people control it |
| Compliance | Tax and National Insurance paid on time in the past |
The compliance test is the one that fails, and it fails for reasons that have nothing to do with construction: a late CT600, a PAYE payment a few days over, a VAT return submitted after the deadline. Losing gross payment status is materially worse than never having had it, because the cash flow effect of a sudden 20 percent deduction on every invoice lands immediately. Keeping the CT600 filed on time is therefore a CIS control as much as a corporation tax one. The rules on when HMRC can now remove it, including the fraud-connected cancellation powers, changed in April 2026, and we covered those separately in CIS compliance changes 2026.
Records, and the monthly routine that makes all of this boring
Records must be kept for at least three years after the end of the tax year they relate to: the gross amount invoiced excluding VAT, the deductions made, and where a deduction was made, the materials costs the subcontractor invoiced excluding VAT. HMRC can ask at any time, and failing to produce them carries a penalty of up to £3,000.
The whole scheme collapses into one repeating calendar. A practice running CIS for several clients should be working to this, not to a list of individual deadlines.
| When | What happens |
|---|---|
| At onboarding, before any payment | Settle employment status, then off-payroll, then CIS scope. Save the CEST output. |
| Before the first payment | Verify with HMRC. Record the verification number and the rate. |
| 6th to 5th | The tax month. Log payments, split labour from materials, hold the receipts. |
| By the 19th | Issue payment and deduction statements for the month just ended. |
| By the 19th | File the CIS300, or a nil return, and submit the EPS for deductions suffered. |
| By the 22nd | Pay HMRC electronically. The 19th if you pay by post. |
| Rolling | Watch the £3 million deemed contractor test and the two year re-verification window. |
How Acenteus Accounting helps
CIS is high volume, low judgement, entirely checkable work with a hard monthly deadline, which is exactly the shape of process that suits an outsourced team. We run the cycle for contractor clients as part of our accounting services for small businesses: the verification log, the labour and materials split, the statements, the CIS300 and the EPS. The judgement calls, employment status above all, stay with you and the client.
The reason we keep CIS and payroll together rather than splitting them is the EPS. Deductions suffered have to reach the payroll submission by the 19th or the client pays PAYE it does not owe, so the two sit inside the same bookkeeping and payroll service rather than being handed between teams. The VAT side, including reverse charge coding, runs through the same route as the rest of our tax compliance outsourcing.
For practices, the question is usually whether CIS is worth taking in house at all. A contractor client with 30 subcontractors is a fixed monthly block of work that cannot move and does not scale with fee income. It is worth comparing that block against what bookkeepers charge in the UK before adding headcount for it. How an engagement is structured is set out on our outsourcing for UK accountants page.
Where a subcontractor is incorporating, the CIS position changes at the same time as everything else, because the deductions stop coming back through Self Assessment and start coming back through payroll. Getting the payroll scheme open before the first invoice is part of setting the business up, and that timing sits alongside the other incorporation steps in our guide to setting up a limited company in the UK.
You do not have to take that from a service page. Our Clutch profile carries a 5.0 rating across three client reviews. Shobhana Solanki, Managing Director of TAXTEK CAMBRIDGE LTD in Cambridge, wrote that our “openness to questions and feedback fostered a positive working relationship, which helps to build trust”. A director at a financial services company in Northern Ireland wrote that we “provide high-quality work at a cost-effective rate”. The same reviews ask for closer workflow alignment, which on a monthly deadline like CIS is the right thing to push on, and it is the part we agree the calendar for at the start.
If you want a number rather than a conversation, send us the subcontractor count and a sample invoice and we will tell you what the monthly cycle costs to run.
Frequently Asked Questions (FAQ)
Runs the monthly cycle: employment status checks, subcontractor verification with HMRC, the labour and materials split on every invoice, payment and deduction statements within 14 days of the tax month end, the CIS300 by the 19th, the EPS for deductions suffered, and the records HMRC can ask for at any time.
By the 19th of every month following the last tax month. Tax months run from the 6th to the 5th, so the month ending 5 June has a return due by 19 June. Electronic payment of the deductions is due by the 22nd, or the 19th if you pay by post.
£100 at one day late, £200 at two months, then £300 or 5 percent of the deductions at six months and again at twelve months, whichever is higher. Beyond twelve months it can reach £3,000 or 100 percent of the deductions. You have 30 days from the notice to appeal.
Take the invoice total, remove VAT, materials the subcontractor paid for, consumable stores, fuel that is not travel, plant hire for the job and manufacturing or prefabricating costs. Apply the rate to what is left. On a £6,000 invoice with £1,500 of materials and £500 of plant hire, 20 percent applies to £4,000, giving £800.
20 percent for a registered and verified subcontractor, 30 percent where the subcontractor is unregistered or cannot be verified, and 0 percent where they hold gross payment status.
No. You do not need to verify again if you have included them on a CIS return in the current or the last two tax years. Outside that window they need verifying again before you pay them.
No. HMRC states in its Business Income Manual that being registered as a CIS subcontractor is not proof of self-employed status. Status is decided on the facts of the engagement, and getting it wrong leaves a PAYE and National Insurance liability behind a scheme that looked compliant.
Off-payroll working. HMRC's Employment Status Manual says that where payments are subject to PAYE under the off-payroll rules you do not need to consider CIS. Only if those rules do not apply do you go on to consider whether CIS deductions are due.
File a nil return or ask HMRC to treat you as inactive. Doing nothing counts as a late return and triggers the £100 penalty.
Once it has spent more than £3 million on construction operations in the previous 12 months. It is a rolling test, so the obligation can start mid-year, and it applies even though the business does no construction work itself.
Report the deductions suffered year to date on an Employer Payment Summary by the 19th and set them against the PAYE bill. Any excess is claimed as a refund after the tax year ends, once all FPS, EPS, CIS and Company Tax returns are filed. HMRC usually responds within 8 weeks.
When the customer is registered for both VAT and CIS, the services fall within CIS, the supply is standard or reduced rated, the supplier is not an employment business, and the customer has not given written end user or intermediary notification. Zero rated work is outside it.